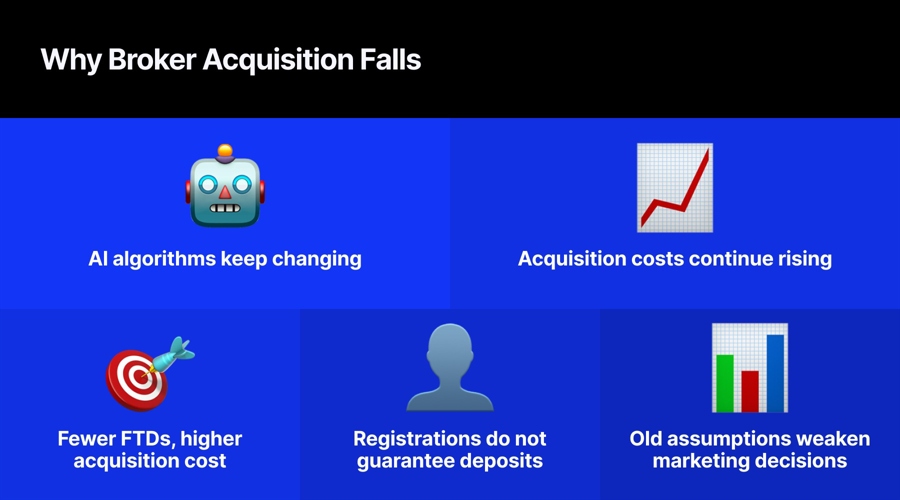
Over the past few weeks, I have spoken with people across several CFD brokers. Different companies, different markets, but the complaint was remarkably consistent: campaigns that worked in May and June were delivering fewer first-time depositors by the end of Q3. Cost per acquisition and overall customer acquisition costs were rising, and management wanted answers.
London’s trading industry is coming home!
Some brokers questioned their marketing teams. Others looked toward new agencies. I understand the instinct. Acquisition budgets are expensive, and declining results demand action. But I think the industry is asking the wrong question.
Instead of asking who failed to deliver the FTDs, perhaps we should ask why brokers with years of client and trading records still rely so heavily on yesterday’s marketing assumptions.
The Algorithms Really Did Change
This year, the advertising giants continued their shift toward AI-driven optimization. Google began automatically upgrading eligible Search campaigns using certain older settings to AI Max in September. TikTok revised its Smart+ system during Q3, combining automated and manual controls. LinkedIn expanded automated creative testing, while Meta continued developing models that learn across its advertising surfaces.
Not every change happened in Q3, and none proves that algorithms caused every broker’s declining performance. Competition, creative fatigue and changes in client demand also matter. Financial advertising faces additional restrictions: Google permits eligible CFD campaigns only under licensing and certification rules, while Meta has long prohibited direct CFD promotions.
Nevertheless, one thing is clear. The systems deciding who sees an advertisement are evolving rapidly. Running October’s campaigns on May’s assumptions is risky.
But the real failure may not be that brokers cannot control these algorithms. It may be that they have neglected the one advantage they do control: their own data.
Sitting on a Gold Mine, Marketing with a Guess
A CFD broker can know far more about its clients than any advertising agency looking at a campaign dashboard. It can see where funded clients came from, how long they took to deposit, where onboarding failed, which instruments they traded, how often they returned and what happened after their first deposit.
Does a particular market attract traders interested primarily in gold, while another brings more activity in indices? Do certain campaigns attract registrants who never pass verification? Does one source generate inexpensive FTDs who disappear after a week, while another brings clients who remain engaged for months?
These are questions for data, not instinct.
Yet in my experience, marketing discussions too often start with familiar beliefs: gold works in this region, forex performs in that one, this audience is younger, this creative converted last quarter. Industry experience matters. I have relied on it throughout my career. But experience should generate hypotheses, not substitute for evidence.
I cannot claim that most brokers fail to use big data without a comprehensive industry study. What I can say is that the gap between the information a broker collects and the information its marketing team actually uses deserves far more attention.
A Registration Is Not a Business Outcome
Here is where the disconnect becomes expensive. An ad platform may report excellent results because it finds people likely to click or register. But brokers are not paid for clicks, and a registration is not a funded account.
Even FTD numbers alone do not tell the whole story. An acquisition channel must be assessed against the cost of attracting eligible clients, the quality of the onboarding process, retention and sustainable revenue. Full customer acquisition cost includes more than media spend.
If a broker sends an advertising system only registration events, it risks teaching the system to find registrations. Google’s enhanced conversions for leads and offline conversion capabilities are designed to connect advertising activity with later outcomes; its 2026 changes to conversion data infrastructure make accurate implementation even more relevant.
That does not mean uploading clients’ trading histories into an advertising platform. It means connecting permitted, reliable conversion signals to campaigns and conducting deeper analysis inside the brokerage.
The more AI automates advertising, the more important the quality of those signals becomes.
The Solution Is Not Another Agency
Before spending another million on acquisition, I would start with a simple exercise: put marketing, CRM, platform activity, onboarding, deposits and revenue data into one analytical view. Not another dashboard full of impressions and clicks. A view that follows a client from first touch to funded account and beyond.
Then compare cohorts. Look at acquisition source, market, onboarding completion, instrument preferences in aggregate, engagement and retention. Identify where conversion dropped between June and October. Separate rising media prices from weaker registration-to-deposit conversion. Test whether the problem appeared across every channel or only certain campaigns.
If aggregate data shows strong interest in gold, test relevant, compliant educational content rather than generic advertising. Only then should a broker change budgets, audiences, creative strategies or agencies.
Big data does not mean buying an expensive piece of software and calling it transformation. It means building the ability to ask better questions and test the answers. Sometimes the result will prove the marketing team underperformed. Sometimes it will expose weak tracking, an onboarding bottleneck or a product that no longer matches the audience.
And because these are financial products, the analysis needs boundaries. Use aggregated insights where possible, respect data protection laws and platform policies, and never use trading losses or signs of vulnerability to target people with more speculative advertising. ESMA has repeatedly stressed the need for appropriate target markets and investor protection for complex derivatives.
Understanding customers is not the same as exploiting them.
The Advantage Brokers Already Own
Google, Meta, TikTok and LinkedIn will keep changing their systems. No marketing director can prevent that. What brokers can change is their dependence on assumptions.
When FTDs fall and acquisition costs rise, replacing a marketing team may feel decisive. But if the next team receives the same incomplete data and the same flawed measurement, why should anyone expect a different result?
Our industry has spent years collecting extraordinary amounts of information about how clients arrive, trade and stay. The competitive advantage is no longer simply having that data. It is turning it into decisions.
Before asking who to fire, I would ask one question: do we actually know our clients, or do we just know how much we paid to acquire them?
This article was written by Badea Alexandru Gabriel at www.financemagnates.com.Retail FXRead More
You might also be interested in reading Short bets on most consumer staple stocks rose in July.