After a decade of product proliferation, mobile interface optimization, and the quest for customer acquisition, some of the most important competitive questions are moving below the screen: who controls the infrastructure, who carries the operational risk, and who can be trusted to keep the system working when the interface changes?
For much of the past, financial technology was built around unbundling, with specialized applications promising a better experience for trading, saving, payments, or any other finance-related services. That model created genuine innovation and choice. But interface differentiation alone is becoming harder to sustain.
London’s trading industry is coming home!
Fee pressure, complex tax environments, and rising capital and operating requirements across fragmented European markets are making scale and operational depth more important.
The European Fund and Asset Management Association (EFAMA) reported that operating profit margins fell to 11.1 basis points of average AuM in 2023, the lowest level since the 2008 financial crisis. EFAMA attributed the pressure to persistent fee erosion and rising costs, including technology expenditure.
Europe’s Bank-Centred Baseline
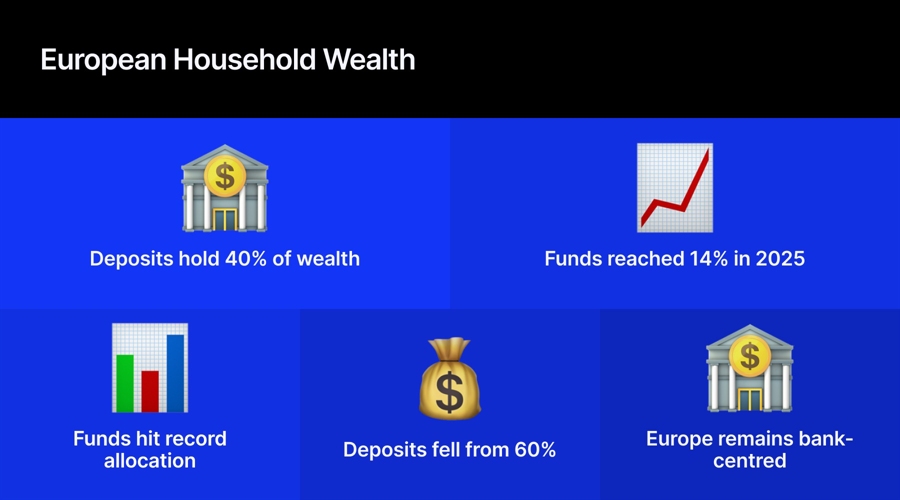
Europe starts from a distinct financial baseline defined by bank-centred wealth. In July 2026, EFAMA reported that European households still held 40% of their financial wealth in bank deposits, only modestly below the 42% peak reached in 2022 and higher than the 37% level seen in 2015.
That persistence reflects the long-standing role of banks as the primary financial relationship for European households. Yet household allocations are gradually shifting: deposits accounted for 45% of new financial acquisitions after 2020, down from 60% between 2015 and 2019, while investment-fund holdings reached a record 14% of household assets in 2025.
Policy measures such as Savings and Investment Accounts (SIAs), now implemented across more than a dozen European countries, are designed to accelerate that transition, but the data suggest that the reallocation of household wealth remains an evolutionary process.
Integration Without Full Ownership
Integration, however, does not require one institution to own every link in the chain. Open banking, specialist custody and clearing, embedded finance, and white-label infrastructure have made it possible to combine services from different providers while presenting customers with a unified experience.
Vertical integration can offer greater control and potentially better economics, but it also brings more capital requirements, regulatory responsibility, and operational complexity.
Freedom24 provides one example of that trade-off, combining centralized, digital-first Tradernet technology and physical infrastructure with operations serving different European markets. The broader lesson is that European scale increasingly depends on technology that can be centralized without becoming rigid at the local level.
When the Interface Becomes Programmable
The more consequential shift is happening at the interface itself. Open APIs, embedded finance, and programmatic trading have already separated parts of the customer experience from the institution that provides the underlying service. Artificial intelligence extends that separation.
Protocols such as the Model Context Protocol (MCP) give AI applications a standard way to work with external data and tools. Mobile applications are not going away; they remain important for onboarding, identity verification, and client relationships. But an app no longer has to be the only door into a financial platform.
As conversational AI, automated portfolio tools, and agentic systems develop, a customer may increasingly express an investment intention through one interface while another institution performs the underlying financial service. That creates a harder strategic question: if the interface can move, where does the durable value remain?
In the first few weeks of agentic trading on Robinhood, over 50,000 customers have opened agentic trading accounts and are trading millions of dollars per day of equities and options.Writing and executing sophisticated strategies or optimizing your everyday spending no longer…
— Vlad Tenev (@vladtenev) June 18, 2026
Infrastructure Is Not Enough
There is a strong case for saying “infrastructure.” There is also a good reason to be cautious. Technology history is full of examples in which the company closest to the customer captured the economics while the systems underneath became increasingly interchangeable.
Search, digital marketplaces, and parts of communications all demonstrate the power of aggregation. An AI agent that can compare providers, route transactions, and negotiate on behalf of a customer could put similar pressure on brokerage infrastructure.
The answer, then, cannot simply be that infrastructure wins. Value will remain where substitution is difficult.
In finance, that can mean regulated market access, custody, liquidity, financing, execution quality, proprietary information, or the ability to manage risk across jurisdictions. None of these advantages is permanent. But a provider that combines several of them may be harder to replace than one that offers little more than connectivity.
A Broader Set of Capabilities
That also changes the economics. If software agents can compare execution and move between providers, a basic transaction fee becomes a less convincing moat.
Infrastructure providers will need to earn from a wider set of capabilities, whether through custody, financing, securities lending, foreign exchange, liquidity, data, or differentiated execution. The key question is not simply who owns the balance sheet or the licence, but who can combine scarce capabilities in a form that other interfaces can actually use.
The same logic applies to institutions of very different sizes. Global custodians can rely on scale in post-trade infrastructure. Specialist brokers and technology providers may compete on market access, execution, distribution, or particular operational capabilities.
The European market is unlikely to collapse into a single winning model; the more interesting question is how these layers connect and which of them remain genuinely difficult to replace.
The Financial Rails May Also Change
The underlying rails may change as well. Tokenization and distributed ledgers are already being tested as alternatives to parts of the traditional financial stack.
In its April 2026 analysis of tokenized money-market funds, the European Central Bank identified faster settlement, near-24/7 availability, and programmability as potential benefits while also highlighting liquidity and operational risks.
The technology can change how the system works without eliminating the underlying jobs of authorization, settlement, liquidity, and risk management.
Rethinking Human Oversight
The rise of automated execution also changes what “human oversight” needs to mean. A person cannot reasonably approve every routine transaction in a high-speed system.
In a mature agentic architecture, people would instead define the authority under which software can act: what the system is allowed to do, within what limits, and what events require escalation or intervention.
That is broadly consistent with the human-oversight approach in Article 14 of the EU AI Act, which emphasizes proportionate safeguards and deployer controls rather than continuous manual intervention.
Governance Moves Into the System
Governance therefore moves closer to the machinery of finance itself. Legal rules, compliance requirements, and risk limits increasingly have to be translated into system permissions, API controls, monitoring, and transaction records that can be reconstructed after the fact.
The 2026 Oxford–GlobeScan survey illustrates why this matters beyond technology teams: geoeconomic risk ranked first among respondents at 76%, while AI and technology risk rose from 17% in 2025 to 44%, and governance reached 45% among ESG-related reputational concerns.
The Fight Beneath the Interface
The interesting fight will not be between an app and an API. It will be over what sits underneath both.
If an AI agent can choose among financial providers, the providers best positioned to retain value will be those that still offer something the agent cannot treat as interchangeable: reliable market access, execution, regulated custody, financing, data, core technology and delivery stack, or a combination of them.
At the end of the day, the interface may or may not fundamentally change, and once more again after that. The underlying test is whether the institution remains valuable when the customer no longer has to enter through its front door.
This article was written by Valentin Shatalov at www.financemagnates.com.Retail FXRead More
You might also be interested in reading MILLIONS of motorists could be driving unsafe vehicles because they ignore mechanics’ recommendations.